BlackBerry posts record QNX quarter but stock slips 7%
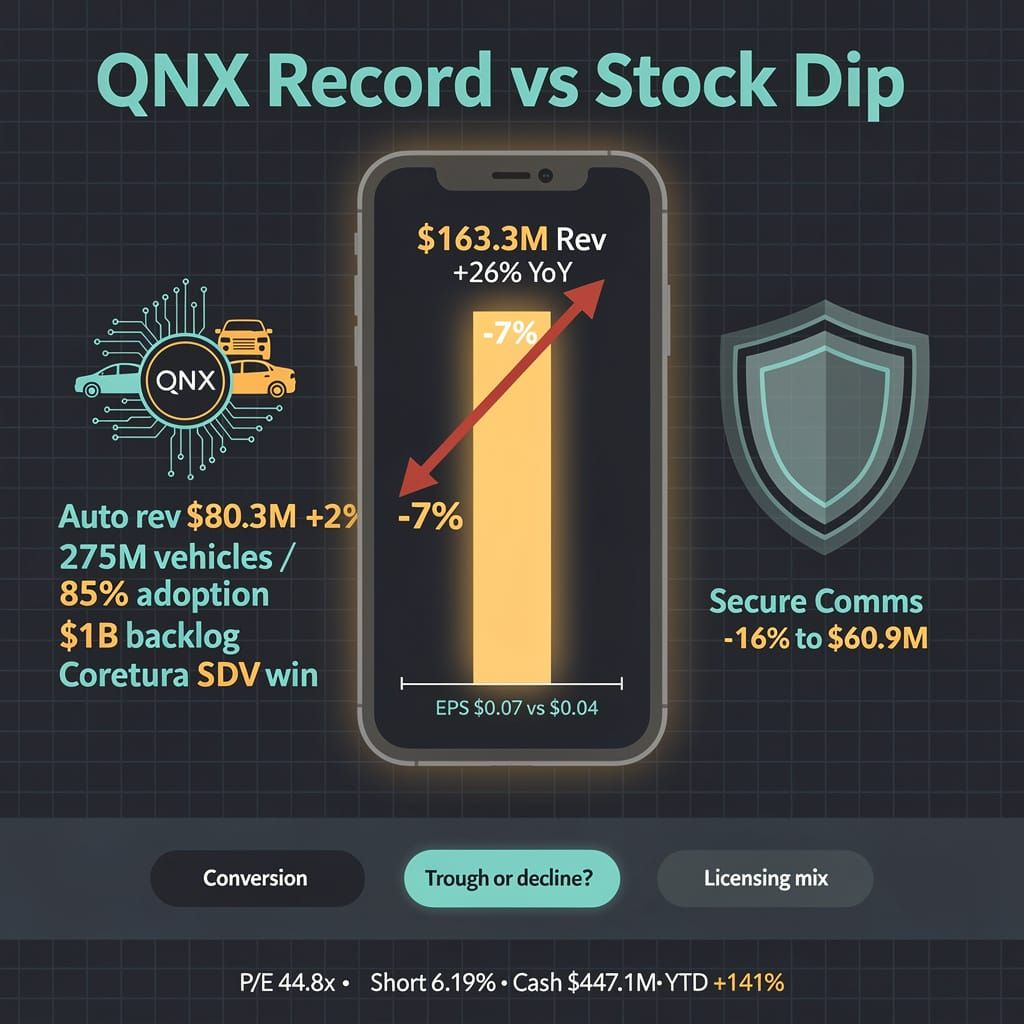
BlackBerry beat EPS ($0.07 vs $0.04) and revenue ($163.3M vs $142.5M), with QNX hitting a record $80.3M — roughly 275M vehicles on its runtime.📉 Yet the stock slipped 7% as Secure Communications fell 16% and Q3 is implied below Q2. Record results, but the market is only trusting near-term royalty conversion. Is the dip a buying window or a warning on QNX's lumpy pipeline? 💭
On September 24, 2026, BlackBerry delivered what looked like a headline-chasing beat: Q2 fiscal 2027 adjusted EPS of $0.07 against a $0.04 consensus, revenue of $163.3 million versus a $142.5 million projection, and 26% year-over-year growth. GAAP net income swung to $33.9 million. Yet the stock fell roughly 7% within days of the print — even as shares sit up about 141% year-to-date per RBC Capital.
The gap between the income statement and the ticker reveals how value, risk, and leverage have shifted inside BlackBerry's portfolio — and what investors are now choosing to discount.
A Record QNX Quarter and a Landmark Design Win
The revenue surge traces almost entirely to licensing rather than recurring software. QNX automotive revenue grew 27% to a record $80.3 million — now more than half the company's total. Underpinning that: the September 22 announcement that Coretura AB (the Daimler Truck and Volvo Group joint venture) selected BlackBerry's QNX-based Alloy Kore as the safety-certified foundation for its software-defined vehicle platform. It is the first named design win for Coretura's SDV initiative, converting a multi-quarter pitch into a concrete program valued at more than $100 million in royalty backlog.
Design wins convert to revenue over a multi-year production cycle, which is why management raised its fiscal 2027 revenue outlook to $616–$636 million and guided QNX to $315–$325 million.
Incentives matter here. CEO John Giamatteo, in place since late 2023, has staked his turnaround on QNX penetrating vehicle production pipelines. QNX now claims roughly 275 million vehicles on its runtime with an estimated 85% automotive adoption rate across nearly every maker except Tesla. Every design win extends a royalty tail across production lifecycles — a predictable base that is inherently lumpy and tied to automaker schedules.
The Counter-Signal the Market Seized On
The concern is the legacy Secure Communications unit. Revenue there fell 16% to $60.9 million, and management guidance points to weakening demand as competitive pressure from open-source and Linux alternatives builds. Investors looked past the record and toward a narrower QNX pipeline conversion: implied Q3 revenue of ~$149 million marks a sequential decline from Q2's $163.3 million.
The market is effectively signaling that near-term QNX royalty conversion — not the backlog — is what it trusts. The run-up into the print carried its own momentum, not all of it tied to fundamentals: on September 21, three days before earnings, a CNBC "Mad Money" Lightning Round buy recommendation from Jim Cramer helped push BlackBerry shares 5% higher to $8.40, with the tech-software ETF IGV up 2% in the same session. The September 24 Coretura announcement then lifted the stock another 7% in Tuesday trading — yet the post-earnings sessions gave much of that back, evidence of heavy selling despite the $1B total QNX backlog. BlackBerry's $447.1 million cash at August 31 provides a cushion, but it also reflects a company generating operating cash without a consistent trajectory across all segments.
Who Gains and Loses Leverage
The licensing-heavy mix gives BlackBerry control of the functional-safety software layer embedded in vehicles — high margins, low support costs per incremental royalty dollar. That shifts negotiating leverage toward the company; every design win compounds. But it concentrates dependency on vehicle production volumes and OEM procurement cycles, transferring cyclical risk directly to the income statement. With a forward P/E near 44.84x and short interest at 6.19% of float, the valuation leaves little room for conversion slippage.
What to Watch
- QNX design-win conversion: Whether the Coretura backlog (part of the ~$950 million–$1 billion total) and other wins translate into the guided $315–$325 million fiscal-2027 QNX revenue, especially in the back half.
- Secure Communications trajectory: Whether Q3's implied sub-$149 million company revenue reflects a trough or a persistent sequential decline.
- Licensing mix and cash: Whether the share of revenue from pure licensing and the $447.1 million balance hold as QNX becomes a larger share of the book.
This is reporting and analysis of BlackBerry's earnings mechanics and market reaction, not an investment recommendation.
Comments ()